statutory severance payments taxable differently
Are statutory severance payments taxable differently? This is a common question among employees who receive compensation following termination, as the tax treatment can significantly affect the net amount received. Statutory severance payments are generally considered income for tax purposes, but their treatment can differ from regular wages and from common law severance payouts. In most jurisdictions, statutory severance is included in the employee’s income for the year it is received, and taxes are withheld at source according to the applicable tax rules. However, certain deductions or special tax considerations may apply depending on local tax laws, which can make the effective taxation of statutory severance different from ordinary salary or other benefits.
Understanding the distinction between statutory and common law severance is crucial for employees planning their finances. Statutory severance payments are the minimum amounts mandated by employment legislation and are calculated based on factors such as length of service, age, and the employer’s payroll size. Common law severance, on the other hand, can include additional compensation for reasonable notice, lost bonuses, or other benefits, often resulting in higher payouts. The tax treatment of common law severance can differ from statutory payments because courts sometimes structure awards in ways that separate amounts intended to compensate for lost future income versus amounts for actual notice. This makes the comparison in Statutory vs common law severance federal frameworks particularly relevant for understanding how different types of severance are taxed.
Another consideration is the timing of the payment. Statutory severance is usually paid as a lump sum shortly after termination, which may push the employee into a higher marginal tax bracket for that year. Common law severance, especially when negotiated or awarded through a settlement, may be structured in installments or allocated to cover multiple years of income, potentially reducing the overall tax burden. These differences highlight the practical importance of understanding both statutory rules and common law entitlements when evaluating net severance income.
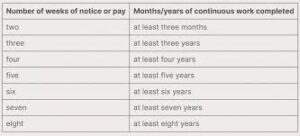
Are statutory severance payments taxable differently?
Employers also play a role in how statutory severance is taxed. In some cases, they may be required to withhold taxes at source according to payroll rules, while in others, employees must report the payments as income and pay taxes directly. This distinction can affect the employee’s cash flow and may require planning to avoid unexpected tax liabilities. Comparing Statutory vs common law severance federal treatments, employees can see that common law severance awards sometimes allow for tax planning strategies that are not available for strictly statutory payments, particularly when settlements are negotiated with the assistance of legal counsel.
Employees should also be aware that some jurisdictions allow certain deductions or tax relief for severance payments, particularly if they include amounts related to lost benefits or damages for wrongful dismissal. This further differentiates statutory severance from common law awards, which may include broader categories of compensation that are treated differently under tax law. Consulting a tax professional is often recommended to understand the full implications of any severance payment.
In conclusion, statutory severance payments are generally taxable as income but may be treated differently from common law severance in terms of withholding, timing, and deductions. Understanding these differences is important for employees to plan for their net financial outcome. When analyzed in the context of Statutory vs common law severance federal frameworks, it becomes clear that while statutory payments provide a minimum guaranteed benefit, common law severance often allows for more flexibility in both compensation and tax planning.
